SpaceX shares topped $160, but Morgan Stanley considers them undervalued.
- Morgan Stanley analysts still believe that SpaceX's share price return to $160 is a result of undervaluation.
- The target price is set at around $300.
On October 5, SpaceX shares rose above $160, continuing their gains after a 7% jump on Friday. At the time of writing, SPCX was trading at $167, giving the company a market capitalization of $2,27 trillion.
Against this backdrop, Morgan Stanley reiterated its $300 target price, calling the current price lower than the actual price.
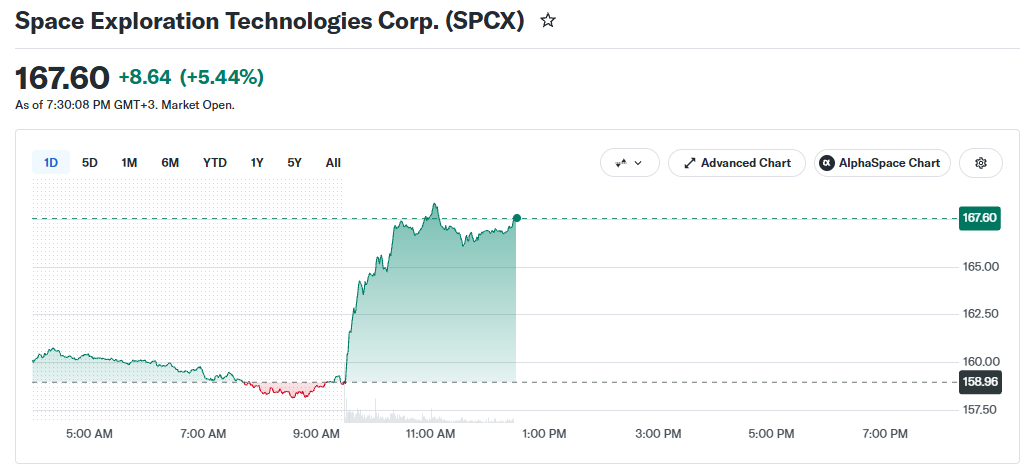
Source: Yahoo Finance
The rise in SpaceX shares has pushed Elon Musk's net worth back above $1 trillion. After the market opened on October 5, Forbes estimated his net worth at over a trillion dollars. This figure refers to the estimated value of the entrepreneur's assets, not his liquid assets.
Why a $2,2 trillion company might be considered undervalued
Morgan Stanley analyst Adam Jonas maintained his "Buy" rating and $300 price target on SpaceX. He titled his note "Cheap and Getting Cheaper."
At first glance, this valuation seems paradoxical. At around $159, SpaceX was trading at roughly 30 times expected 2028 operating profit, while the median for the group of major AI-related tech companies was 16 times.
However, Jonas suggests considering not only the business's value but also its expected growth rate. Morgan Stanley's enterprise value to growth-adjusted operating profit ratio yields a ratio of approximately 0,3 for SpaceX, compared to a median of 0,5 for peers. Even at $300, the analyst estimates the ratio at 0,6, comparable to Amazon and below Alphabet and MetaTrader.
In other words, Morgan Stanley isn't claiming that SpaceX is cheap by traditional multiples. The bank's investment thesis is that the high price can be justified by even higher expected growth rates.
Artificial intelligence has become a major part of the assessment
The bank values SpaceX's space and communications business at approximately $127 per share. At a price of approximately $159, the market, according to Jonas's calculations, would leave only about $32 for the artificial intelligence business.
Morgan Stanley's own model paints the opposite picture. The bank values the corporate AI business at approximately $165 per share, communications, including Starlink, at $118, and commercial launches and assets related to X and Grok at approximately $8. The AI valuation already includes a 50% discount due to the risk of implementation.
The cost of computing power remains the key variable. Jonas notes that even a small change in the lease price can significantly impact future revenue. According to his data, the market consensus suggests approximately 4,1 GW of capacity at $17,60 per watt, while individual short-term contracts by SpaceX have been valued at $30–50 per watt.
The $300 price target depends on how successfully the company can turn its AI infrastructure into a standalone revenue stream.
Jonas believes that one of the closest markers for the stock price is the 15th test flight of Starship, expected in late October or early November.
The next test will be the third-quarter earnings report, as investors will get more data on the development of computing infrastructure and other new areas.